File Form 3115 with Inkle
Form 3115 is how your business formally switches its accounting method with the IRS. That includes moving from cash to accrual, fixing depreciation, adjusting revenue timing, and catching up on deductions you missed. Inkle prepares it, picks the correct change number, and files it with your return.
What is Form 3115?
The Application for Change in Accounting Method (Form 3115) is how a business formally notifies the IRS of a switch in how it accounts for income or expenses. The most common reason is moving from cash to accrual, though it also covers depreciation corrections and revenue recognition changes. Most changes qualify for automatic consent, meaning you file it with your return and the change takes effect right away.

Who can file Form 3115?
Form 3115 is filed by any US business that wants to change how it accounts for income or expenses. This includes C-corps, S-corps, partnerships, LLCs, and sole proprietors. You also need to file it if you are catching up on depreciation you missed in prior years.
C-corporations
Delaware and other US C-corps changing revenue recognition, switching from cash to accrual, or correcting depreciation.
S-corps and partnerships
Pass-through entities follow their own return deadlines, with the same method-change mechanics.
LLCs and sole proprietors
Single-member LLCs and sole proprietors filing on Form 1040 can change methods the same way.
Catching up on depreciation
Missed depreciation on assets you still own? Claim the full catch-up this year. No prior-year amendments needed.
Cash to accrual switches
Crossing the Section 448 gross receipts threshold? This is the most common reason startups file Form 3115.
R&E under Section 174
Capitalize and amortize specified research costs. Five years for domestic, 15 years for foreign expenditures.
Inkle makes filing Form 3115 simple
Form 1120 is filed by U.S. C Corporations and foreign corporations engaged in a U.S. trade or business. It does not apply to S Corps, LLCs, or nonprofits, which file different tax forms.

We identify the right change, confirm it qualifies for automatic consent, and match it to the correct Designated Change Number.

We compute the true-up, apply the correct spread, and show the working so the number holds up under review.

A dedicated tax expert answers your questions in Inkle chat, with replies on a 12-hour SLA.

The original attaches to your 1120 or 1040 and the signed copy goes to the IRS National Office. Handled for you.
Common method changes
Automatic changes carry a Designated Change Number (DCN). Here are the ones we see most often across US startups.
Switch your overall method from cash to accrual. The most common Form 3115 filing we see from growing startups.
Fix an incorrect depreciation method on assets you still own and take the full catch-up in the current year.
Capitalize specified research or experimental costs and amortize over five years (domestic) or 15 years (foreign).
Deduct repairs or capitalize improvements under the tangible property regulations.
The IRS List of Automatic Changes is the authority for each DCN. Inkle's tax experts confirm your change qualifies for automatic consent and select the exact number before filing.
Deadline
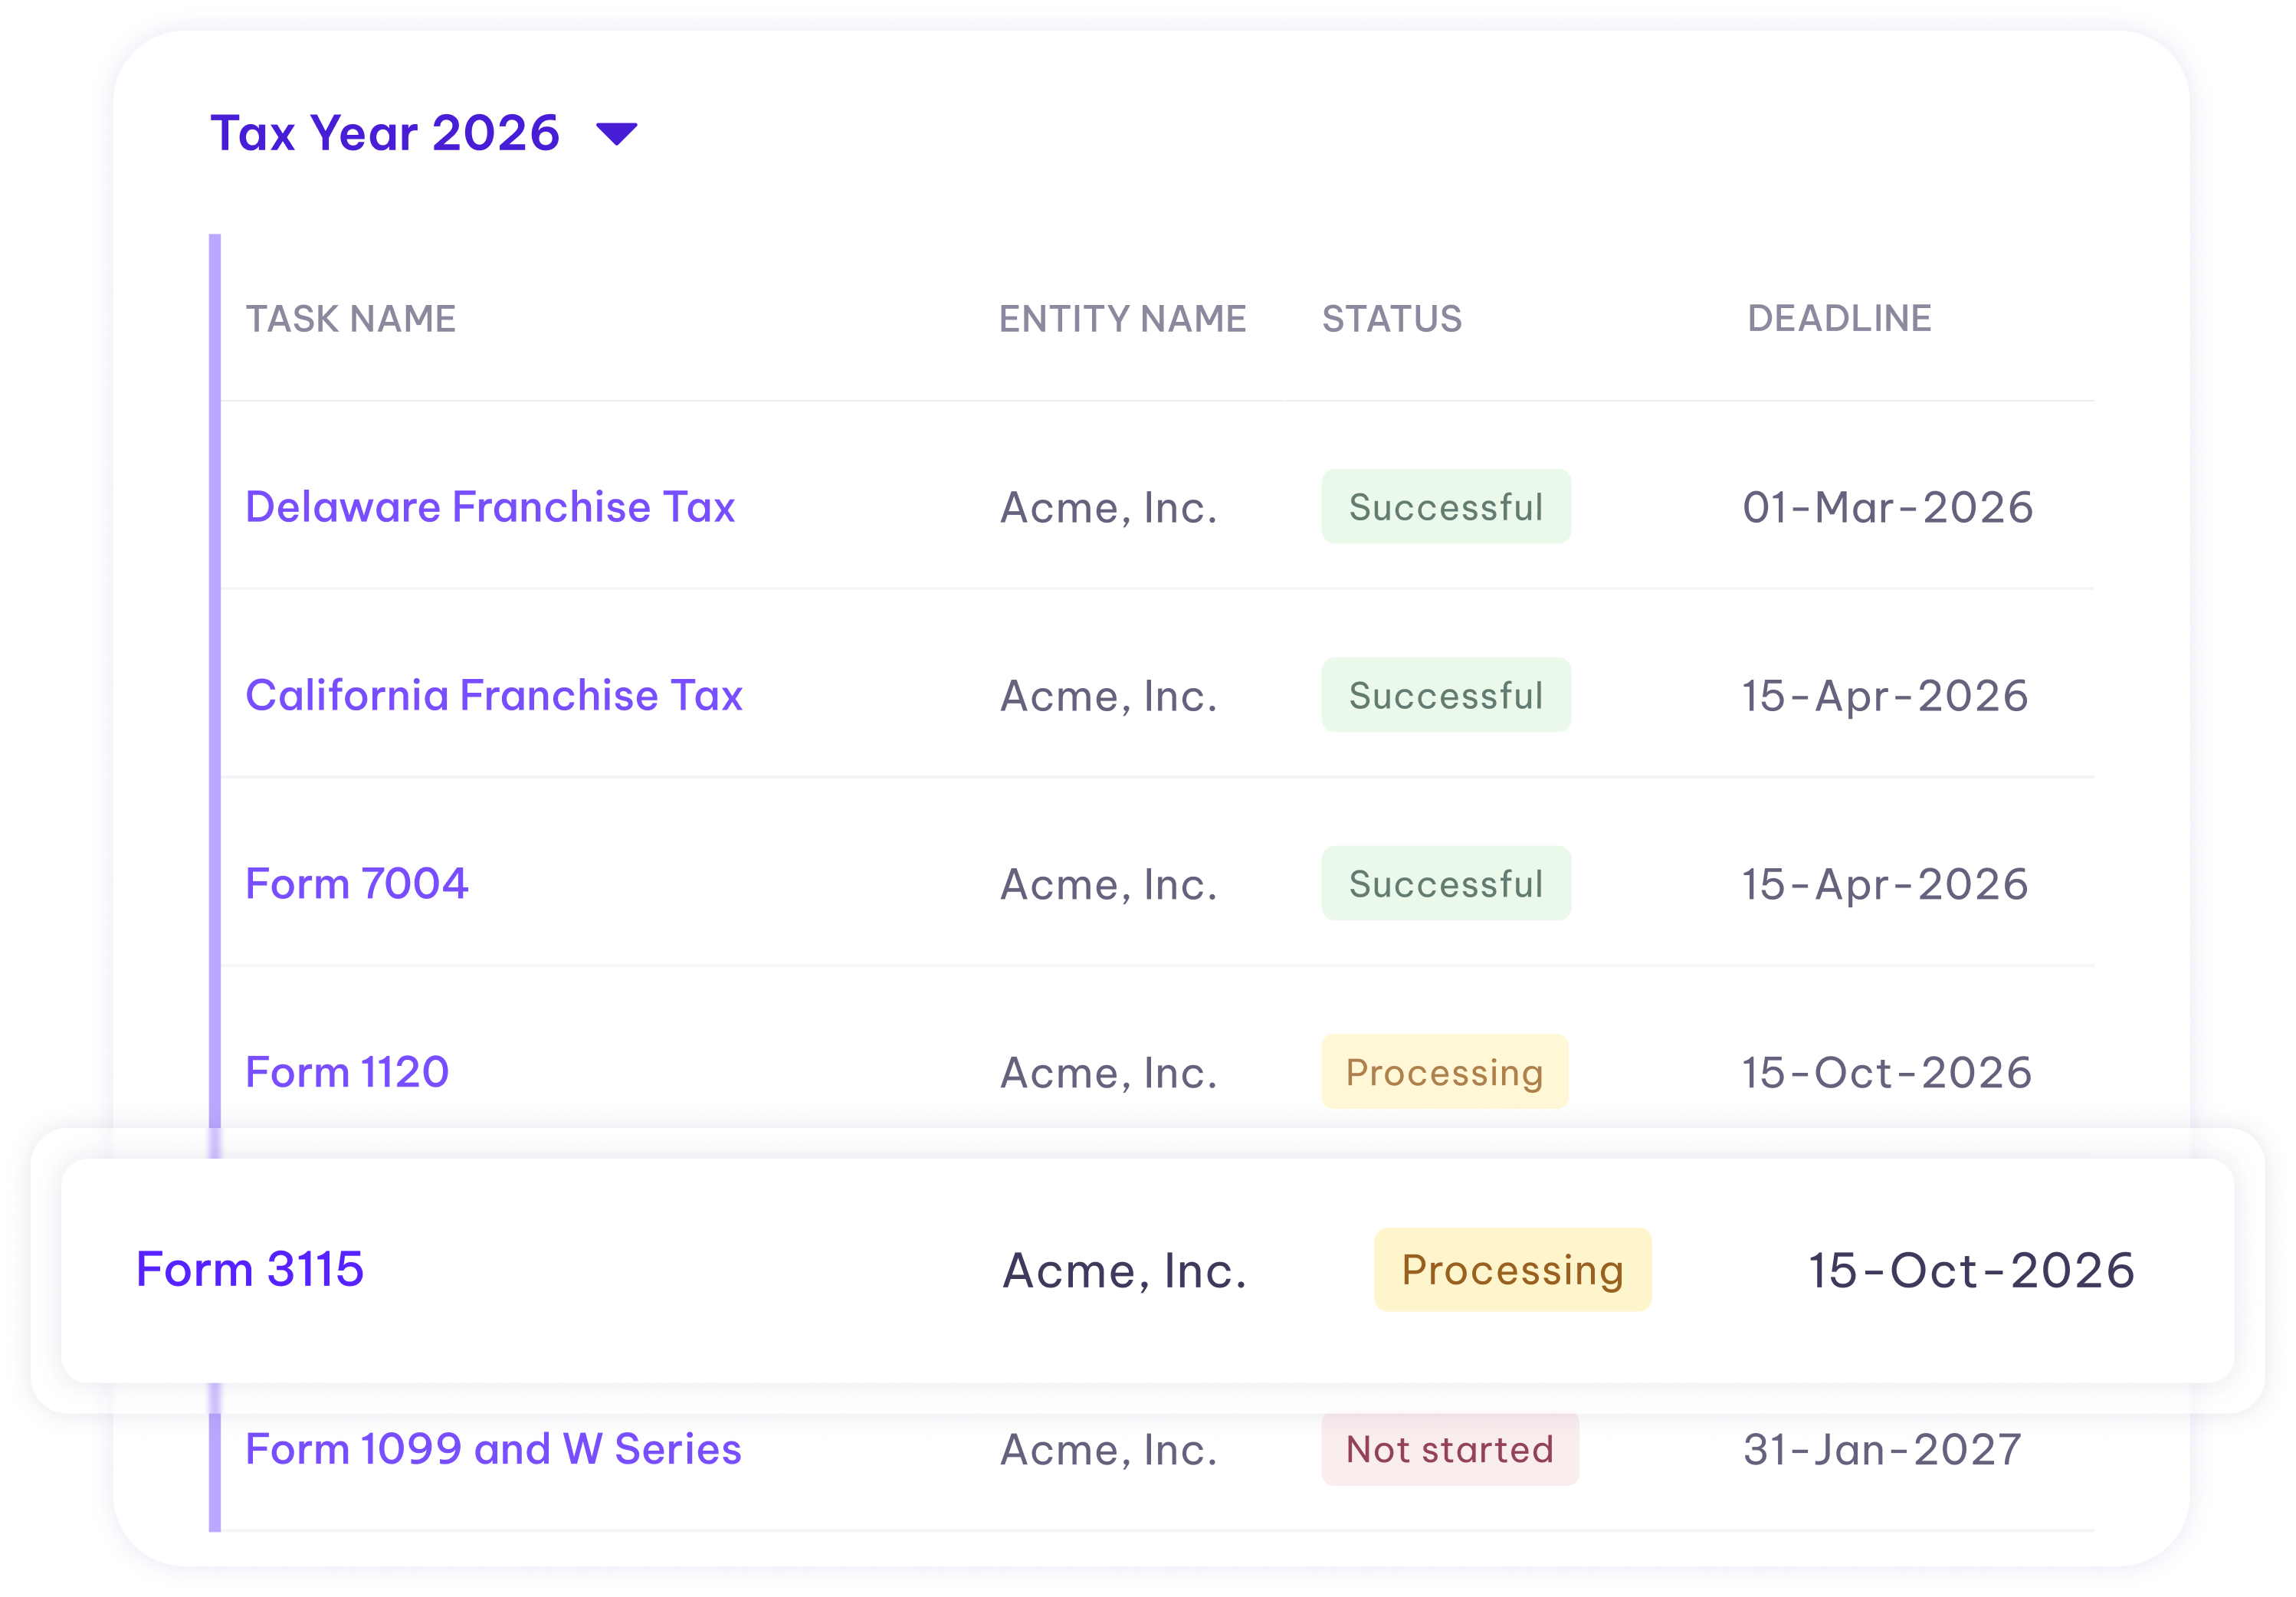
The deadline to file Form 3115 is with your timely federal return, including extensions. For a calendar-year C-corp that is April 15, or October 15 with a Form 7004 extension.
Pro Tip
Filing Form 3115 incorrectly or skipping it when a method change is required can result in the IRS disallowing the change entirely. That can mean back taxes and interest on any underpayment.
FAQs
It is used to request a change in accounting method with the IRS. The most common reason is switching from cash to accrual, but it also covers depreciation changes, revenue timing adjustments, and catching up on missed deductions from prior years.
Any business changing its accounting method, most often moving from cash basis to accrual, or correcting how it has been treating depreciation or a specific item.
Form 3115 covers both automatic and non-automatic changes, and the two follow different procedures.
The one-off correction that prevents income being counted twice or missed entirely when you change accounting method. It captures the cumulative difference as of the change date.
A negative adjustment is generally taken in full in the year of change; a positive one is usually spread across four years. More on Form 3115.
For automatic method changes, no. You file Form 3115 and the consent is deemed given if you follow the procedure.
Non-automatic changes need advance IRS consent, come with a user fee, and can take months. Which category your change falls into is the first thing to establish.
Yes. Correcting depreciation that was understated or overstated in prior years is one of the most common uses of Form 3115, and it usually qualifies as an automatic change.
The catch-up comes through as a section 481(a) adjustment rather than by amending old returns.
Automatic changes are filed with a timely return for the year of change, with a copy to the IRS. Non-automatic changes have to be filed during the year of change itself, which is the tighter constraint.
Missing the window usually means waiting a year. More on Form 3115.
Automatic accounting method changes carry no user fee. Non-automatic changes do, and the amount is set by the IRS and revised periodically.
The fee is separate from whatever your accountant charges to prepare the filing. More on Form 3115.
The current and proposed accounting methods, the year of change, the section 481(a) adjustment calculation, and details of the item being changed, such as the depreciation history for an asset.
Automatic changes attach to a timely filed return. Non-automatic ones need advance IRS consent and a user fee.

